대표어
 한국학술지인용색인(NRF)
권호기사보기
| 기사명 | 저자명 | 페이지 | 원문 | 기사목차 |
|---|
결과 내 검색
동의어 포함
본 연구는 지방정부 간 조세 및 준조세 경쟁을 가능하게 하는 제도적 배경을 살펴보고, 이동성 있는 과세대상의 조세경쟁이 초래하는 부정적 파급효과를 분석하고 그 개선방안을 제시하였다. 현행 탄력세율제도는 자치재정권 확대를 목적으로 도입되었으나, 리스차량, 항공기, 선박 등 이동성 있는 과세대상에 대해서는 지자체 간 세원 유치를 위한 출혈 경쟁을 야기하고 있다. 이러한 경쟁은 개별 지자체의 합리적 선택이 전체 지방세수의 감소를 초래하는 제로섬 게임으로 귀결될 뿐만 아니라, 실제 공공서비스 수혜 지역과 납세지의 괴리를 발생시켜 응익과세 원칙을 훼손한다는 문제가 있다. 나아가 무분별한 세율 인하 경쟁은 지방정부의 실질적인 재정자율성을 오히려 위축시키는 역설적인 결과를 초래하고 있다. 결론적으로 조세경쟁에 대한 적절한 규율은 자치권을 침해하는 것이 아니라 건전하고 지속 가능한 재정 운용을 위한 전제조건이며, 합목적적인 제도 설계가 뒷받침될 때 자치재정권의 실질적인 확대가 가능해질 것이다.
This study examines the institutional background enabling competition over taxes and quasi-taxes among local governments, analyzes the negative spillover effects caused by tax competition for mobile taxable objects, and proposes measures for improvement. Although the current flexible tax rate system was introduced to expand local fiscal autonomy, it has triggered "cutthroat competition" among local governments to attract tax bases for mobile assets such as leased vehicles, aircraft, and ships. Such competition results in a zero-sum game where the rational choices of individual local governments lead to a decrease in total local tax revenue. Furthermore, it undermines the benefit principle of taxation by creating a gap between the actual region benefiting from public services and the place of tax payment. Ironically, indiscriminate competition to lower tax rates ultimately weakens the practical fiscal autonomy of local governments. In conclusion, appropriate regulation of tax competition is not an infringement on local autonomy but a prerequisite for sound and sustainable fiscal management. Substantial expansion of local fiscal autonomy will only be possible when supported by a purposeful and systematic institutional design.*표시는 필수 입력사항입니다.
| 전화번호 |
|---|
| 기사명 | 저자명 | 페이지 | 원문 | 기사목차 |
|---|
| 번호 | 발행일자 | 권호명 | 제본정보 | 자료실 | 원문 | 신청 페이지 |
|---|
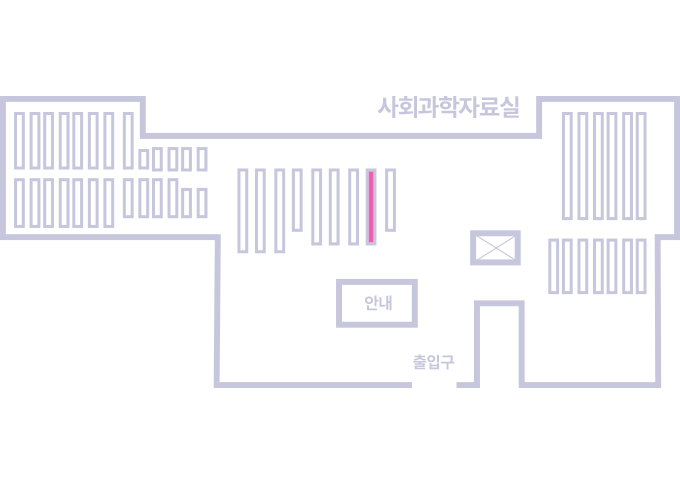
도서위치안내: 정기간행물실(524호) / 서가번호: 국내10
2021년 이전 정기간행물은 온라인 신청(원문 구축 자료는 원문 이용)
우편복사 목록담기를 완료하였습니다.
*표시는 필수 입력사항입니다.
저장 되었습니다.