대표어
권호기사보기
| 기사명 | 저자명 | 페이지 | 원문 | 기사목차 |
|---|
결과 내 검색
동의어 포함
영문목차
Figures=xii
Tables=xiii
Preface=xvii
Part I. Introduction and basic concepts=1
1. Introduction=3
References=6
2. Basic concepts=8
2.1. Stochastic processes=8
2.2. Some commonly used stationary models=11
2.3. Box-Jenkins methods=17
2.4. Integrated variables and cointegration=20
2.5. Spurious regression=28
2.6. Deterministic trend and stochastic trend=29
2.7. Detrending methods=32
2.8. VAR, ECM, and ADL=34
2.9. Unit root tests=37
2.10. Cointegration tests and ECM=39
2.11. Summary=41
References=42
Part II. Unit roots and cointegration=45
3. Unit roots=47
3.1. Introduction=47
3.2. Unit roots and Wiener processes=49
3.3. Unit root tests without a deterministic trend=60
3.4. DF test with a linear deterministic trend=65
3.5. Specification of deterministic trends=72
3.6. Unit root tests for a wide class of errors=74
3.7. Sargan-Bhargava and Bhargava tests=82
3.8. Variance ratio tests=86
3.9. Tests for TSP versus DSP=87
3.10. Forecasting from TS versus DS models=89
3.11. Summary and conclusions=92
References=92
4. Issues in unit root testing=98
4.1. Introduction=98
4.2. Size distortion and low power of unit root tests=100
4.3. Solutions to the problems of size and power=103
4.4. Problem of overdifferencing: MA roots=116
4.5. Tests with stationarity as =120
4.6. Confirmatory analysis=126
4.7. Frequency of observations and power of unit root tests=129
4.8. Other types of nonstationarity=131
4.9. Panel data unit root tests=133
4.10. Uncertain unit roots and the pre-testing problem=139
4.11. Other unit root tests=140
4.12. Median-unbiased estimation=141
4.13. Summary and conclusions=145
References=146
5. Estimation of cointegrated systems=155
5.1. Introduction=155
5.2. A general CI system=155
5.3. A two-variable model: Engle-Granger methods=156
5.4. A triangular system=160
5.5. System estimation methods=165
5.6. The identification problem=173
5.7. Finite sample evidence=175
5.8. Forecasting in cointegrated systems=184
5.9. Miscellaneous other problems=187
5.10. Summary and conclusions=191
References=191
6. Tests for cointegration=198
6.1. Introduction=198
6.2. Single equation methods: residual-based tests=198
6.3. Single equation methods: ECM tests=203
6.4. Tests with cointegration as =205
6.5. Multiple equation methods=211
6.6. Cointegration tests based on LCCA=222
6.7. Other tests for cointegration=226
6.8. Miscellaneous other problems=228
6.9. Of what use are cointegration tests?=233
6.10. Conclusions=241
References=242
7. Econometric modeling with integrated regressors=249
7.1. I(1) regressors not cointegrated=249
7.2. I(1) regressors cointegrated=250
7.3. Unbalanced equations=251
7.4. Lagged dependent variables: the ARDL model=252
7.5. Uncertain unit roots=254
7.6. Uncertain unit roots and cointegration=256
7.7. Summary and conclusions=258
References=258
Part III. Extensions of the basic model=261
8. The Bayesian analysis of stochastic trends=263
8.1. Introduction to Bayesian inference=264
8.2. The posterior distribution of an autoregressive parameter=266
8.3. Bayesian inference on the Nelson-Plosser data=268
8.4. The debate on the appropriate prior=271
8.5. Classical tests versus Bayesian tests=277
8.6. Priors and time units of measurement=277
8.7. On testing point hypotheses=278
8.8. Further comments on prior distributions=284
8.9. Bayesian inference on cointegrated systems=287
8.10. Bayesian long-run prediction=290
8.11. Conclusion=291
References=292
9. Fractional unit roots and fractional cointegration=296
9.1. Some definitions=296
9.2. Unit root tests against fractional alternatives=298
9.3. Estimation of ARFIMA models=300
9.4. Estimation of fractionally cointegrated models=302
9.5. Empirical relevance of fractional unit roots=303
9.6. Summary and conclusions=305
References=306
10. Small sample inference: bootstrap methods=309
10.1. Introduction=309
10.2. A review of the bootstrap approach=309
10.3. The AR(1) model=322
10.4. Bootstrapping unit root tests=325
10.5. The moving block bootstrap and extensions=328
10.6. Issues in bootstrapping cointegrating regressions=332
10.7. Miscellaneous other applications=335
10.8. Conclusions=336
References=336
11. Cointegrated systems with I(2) variables=342
11.1. Determination of the order of differencing=342
11.2. Cointegration analysis with I(2) and I(1) variables=348
11.3. Empirical applications=355
11.4. Summary and conclusions=358
References=359
12. Seasonal unit roots and seasonal cointegration=362
12.1. Effect of seasonal adjustment=364
12.2. Seasonal integration=365
12.3. Tests for seasonal unit roots=366
12.4. The unobserved component model=371
12.5. Seasonal cointegration=375
12.6. Estimation of seasonally cointegrated systems=376
12.7. Empirical evidence=378
12.8. Periodic autoregression and periodic integration=379
12.9. Periodic cointegration and seasonal cointegration=381
12.10. Time aggregation and systematic sampling=381
12.11. Conclusion=382
References=383
Part IV. Structural change=387
13. Structural change, unit roots, and cointegration=389
13.1. Tests for structural change=390
13.2. Tests with known break points=390
13.3. Tests with unknown break points=391
13.4. A summary assessment=398
13.5. Tests for unit roots under structural change=399
13.6. The Bayesian approach=402
13.7. A summary assessment of the empirical work=407
13.8. Effect of structural change on cointegration tests=410
13.9. Tests for structural change in cointegrated relationships=411
13.10. Miscellaneous other issues=414
13.11. Practical conclusions=416
References=418
14. Outliers and unit roots=425
14.1. Introduction=425
14.2. Different types of outliers in time series models=425
14.3. Effects of outliers on unit root tests=428
14.4. Outlier detection=437
14.5. Robust unit root tests=440
14.6. Robust estimation of cointegrating regressions=445
14.7. Outliers and seasonal unit roots=448
14.8. Conclusions=448
References=449
15. Regime switching models and structural time series models=454
15.1. The switching regression model=454
15.2. The Markov switching regression model=455
15.3. The Hamilton model=457
15.4. On the usefulness of the MSR model=460
15.5. Extensions of the MSR model=463
15.6. Gradual regime switching models=466
15.7. A model with parameters following a random walk=469
15.8. A general state-space model=470
15.9. Derivation of the Kalman filter=472
15.10. Harvey's structural time series model (1989)=475
15.11. Further comments on structural time series models=477
15.12. Summary and conclusions=479
References=479
16. Future directions=486
References=488
Appendix 1: A brief guide to asymptotic theory=490
Author index=492
Subject index=500
| 등록번호 | 청구기호 | 권별정보 | 자료실 | 이용여부 |
|---|---|---|---|---|
| 0000790038 | 330.01 M179u | 서울관 서고(열람신청 후 1층 대출대) | 이용가능 |
*표시는 필수 입력사항입니다.
| 전화번호 |
|---|
| 기사명 | 저자명 | 페이지 | 원문 | 기사목차 |
|---|
| 번호 | 발행일자 | 권호명 | 제본정보 | 자료실 | 원문 | 신청 페이지 |
|---|
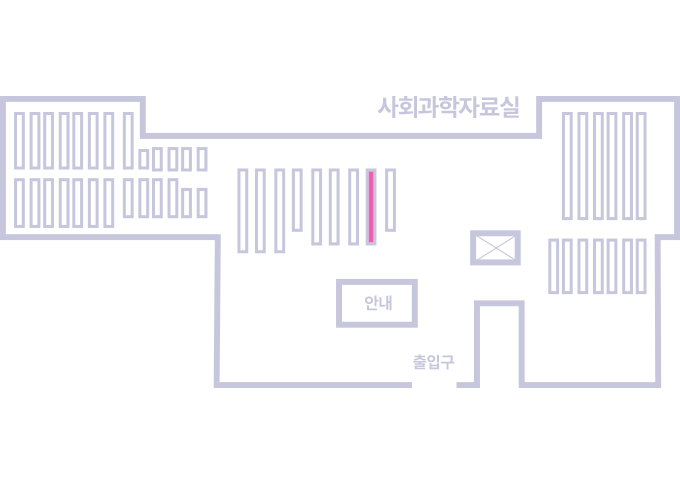
도서위치안내: / 서가번호:
우편복사 목록담기를 완료하였습니다.
*표시는 필수 입력사항입니다.
저장 되었습니다.