대표어
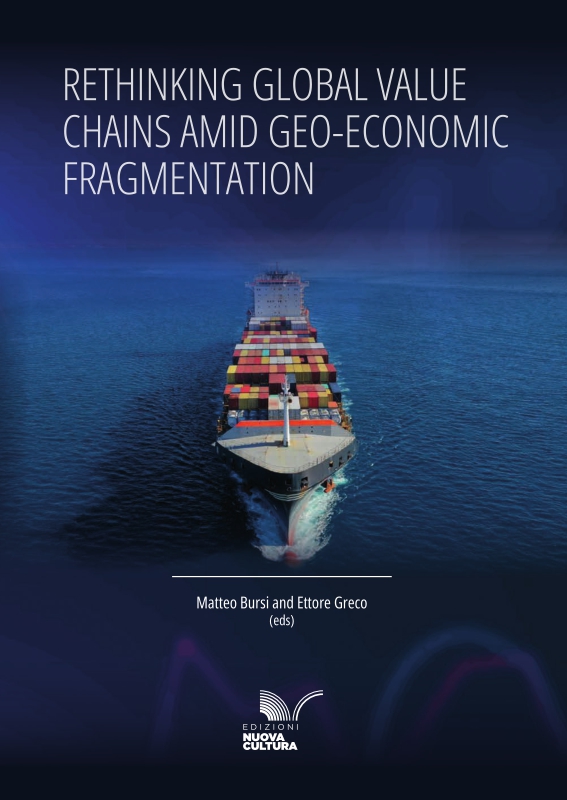
 https://www.iai.it/en/publications/c02/rethinking-global-value-chains-amid-geo-economic-fragmentation
권호기사보기
| 기사명 | 저자명 | 페이지 | 원문 | 기사목차 |
|---|
결과 내 검색
동의어 포함
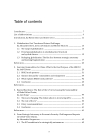
Title page 1
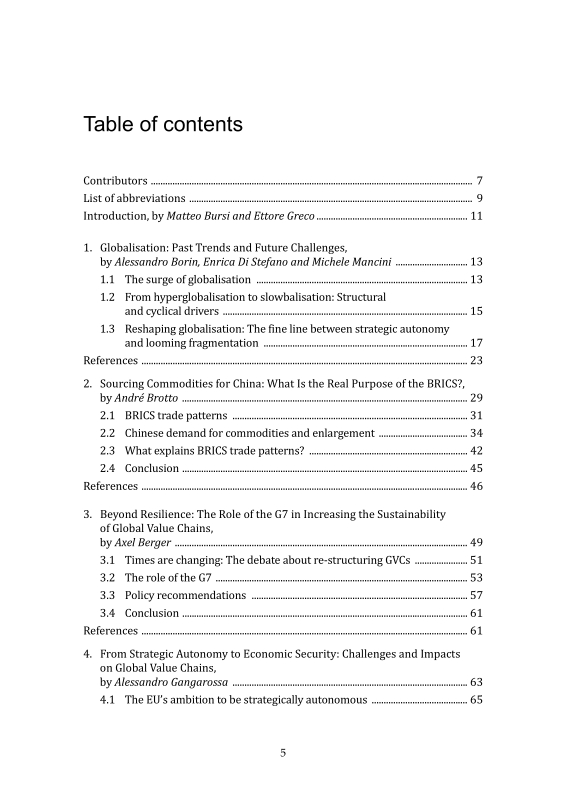
Contents 5
Contributors 7
List of abbreviations 8
Introduction 10
1. Globalisation: Past Trends and Future Challenges 12
1.1. The surge of globalisation 12
1.2. From hyperglobalisation to slowbalisation: Structural and cyclical drivers 14
1.3. Reshaping globalisation: The fine line between strategic autonomy and looming fragmentation 16
1.3.1. The potential consequences of geoeconomic fragmentation 18
1.3.2. The potential effect of recent US protectionist policies 21
References 22
2. Sourcing Commodities for China: What is the Real Purpose of the BRICS? 28
2.1. BRICS trade patterns 30
2.2. Chinese demand for commodities and enlargement 33
2.3. What explains BRICS trade patterns? 41
2.4. Conclusion 44
References 45
3. Beyond Resilience: The Role of the G7 in Increasing the Sustainability of Global Value Chains 48
3.1. Times are changing: The debate about re-structuring GVCs 50
3.2. The role of the G7 52
3.3. Policy recommendations 56
3.4. Conclusion 60
References 60
4. From Strategic Autonomy to Economic Security: Challenges and Impacts on Global Value Chains 62
4.1. The EU's ambition to be strategically autonomous 64
4.1.1. The strategic autonomy trade policy toolkit 64
4.1.2. From theory to practice: The risks of politicisation 67
4.2. The emergence of economic security as the organising principle for GVCs 70
4.2.1. Embedding national security in supply chain policies 70
4.2.2. Emerging approaches to economic security 71
4.2.3. The evolution of the EU economic security agenda 73
4.2.4. The path towards selective openness and strategic interdependence 75
4.3. Conclusion 77
References 78
5. Trade Dependencies after Global Shocks: Are Italy and Other European Economies Diversifying their Supply Chains? 82
5.1. The geography of trade in processed intermediates with high extra-EU dependency 84
5.1.1. Imports of generic and specific processed intermediates 85
5.2. The case of Italy: Evidence of supplier diversification 89
5.3. Conclusions and policy implications 93
References 95
Conclusion 97
1. Globalisation: Past Trends and Future Challenges 13
Figure 1. Ratio between global trade and global output (constant 2015 US dollars) 13
Figure 2A. Determinants of the ratio between trade and output growth 15
Figure 2B. GVC-related trade (share of total trade) 15
Figure 3A. Output elasticity to GVC and non-GVC demand shocks 20
Figure 3B. Difference between GVC and non-GVC demand shocks variance 20
2. Sourcing Commodities for China: What is the Real Purpose of the BRICS? 32
Figure 1. China is diversifying as the concentration of BRIS members changes 32
Figure 2. Please send us your commodities, but maybe not your manufactured goods 34
Figure 3. BRIS+, an opportunity for China to diversify commodity sources 36
Figure 4. Changes in the countries in which China sourced commodities from 2010 to 2021, by commodity type 39
Figure 5. China protects its manufactured products relatively more 42
Figure 6. Tighter BRIS-China relationships might be explained by development finance projects 43
5. Trade Dependencies after Global Shocks: Are Italy and Other European Economies Diversifying their Supply Chains? 87
Figure 1. Italy and the major European economies: imports of generic processed intermediates, by geographic area (percentage share of values, 2019 and 2024) 87
Figure 2. Italy and the major European economies: imports of specific processed intermediates, by geographic area (percentage share of current values, 2019 and 2024) 88
Figure 3. Italy's imports of generic and specific processed intermediates: HH index calculated on the top 20 suppliers, 2005-2024 89
Figure 4. Italy's imports of generic processed intermediates with high extra-EU dependency: growth and import share of the top 15 suppliers 2019-2024 91
Figure 5. Italy's specific processed intermediates with high extra-EU dependency: growth and import share of the top 20 suppliers, 2019-2022 92
*표시는 필수 입력사항입니다.
| 전화번호 |
|---|
| 기사명 | 저자명 | 페이지 | 원문 | 기사목차 |
|---|
| 번호 | 발행일자 | 권호명 | 제본정보 | 자료실 | 원문 | 신청 페이지 |
|---|
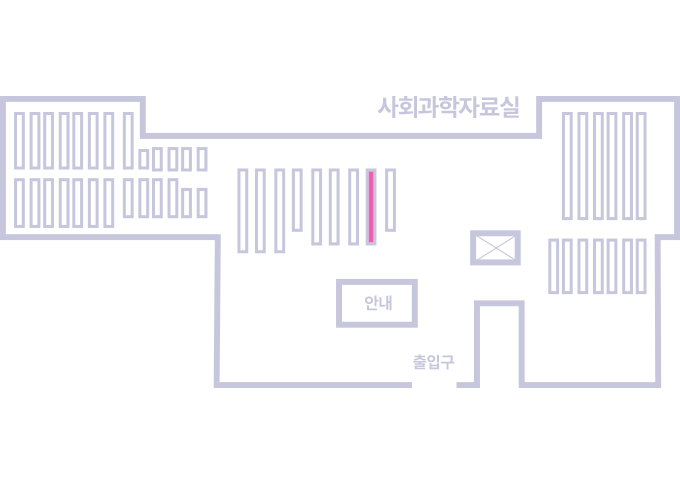
도서위치안내: / 서가번호:
우편복사 목록담기를 완료하였습니다.
*표시는 필수 입력사항입니다.
저장 되었습니다.